Cipla: A Point of Care Diagnostics Business
Turning prescriber reach into test and treat, on ₹954 Cr of capital, 10% of net cash
- Domain
- Product & Strategy
- Kind
- Cipla Ascend Season 2 · Round 1 submission
- Length
- 5 pp · 0.5 MB
What it found
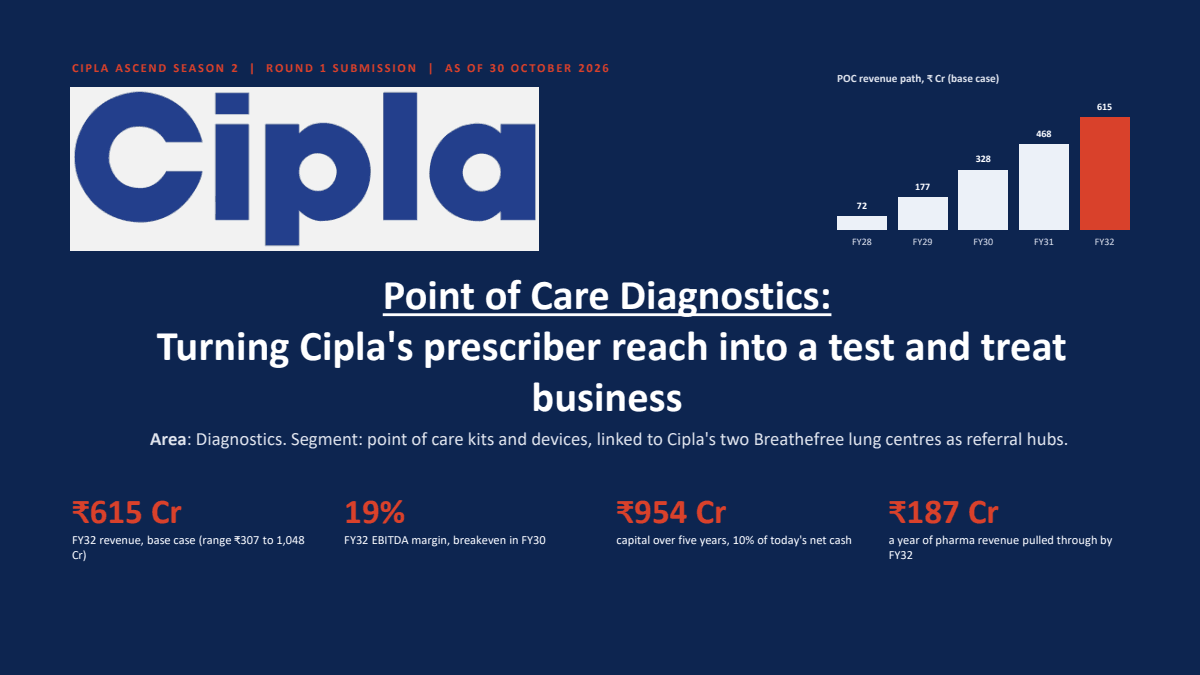
- ₹615 Cr
- FY32 revenue, base case, on labelled assumptions
- 19%
- FY32 EBITDA margin, breakeven in FY30
- 26 of 30
- point of care kits in a five segment screen
Point of care kits
26 of 30
Lung clinics
20 of 30
Path labs
17 of 30
Multispecialty hospitals
13 of 30
Implants and consumables
10 of 30
Five healthcare segments scored on growth, margin, capital needs, channel fit, price freedom and pharma pull, out of 30. The scores are judgement readings of the evidence rather than survey data.
Source: Finding 1; the deck's first slide after the title
Overview
A Round 1 case submission for Cipla Ascend Season 2, recommending that Cipla build a point of care diagnostics business on its prescriber reach. The base case reaches ₹615 Cr of FY32 revenue (range ₹307 to 1,048 Cr) at a 19% EBITDA margin, with breakeven in FY30, on ₹954 Cr of capital over five years. Judgement scores and model inputs are labelled assumptions, and the plan starts with a 50 clinic pilot to replace them with measured values.
Findings
Point of care is where a pharma channel wins. On six criteria it scores 26 of 30, against 20 for lung clinics, 17 for path labs, 13 for multispecialty hospitals and 10 for implants and consumables
India is the engine. In Q2 FY27 India grew 12% while group revenue fell 2% and North America fell 19%, and net cash of ₹9,823 Cr covers the five year plan 10.3 times
The base case stays below listed peers. Its 19% margin compares with Molbio at 22.2%, Metropolis at 24.4% and Dr Lal PathLabs at 28.3%, with cartridges reaching 63% of revenue and ₹187 Cr a year of pharma revenue pulled through by FY32
Idle analysers are the risk to manage first. Molbio's utilisation is 42.3%, so analysers are placed only where clinics commit to 3 tests a day
Capital is released through gates. A 50 clinic pilot reads out by March 2027, 4,000 analysers at 3.5 tests a day are due by FY29, and any acquisition waits until after breakeven