NephroPlus: Initiation of Coverage
India's largest dialysis chain: a growth stock's multiple on prices the government sets
- Domain
- Equities
- Kind
- Independent equity research
- Length
- 15 pp · 0.6 MB
What it found
- HOLD · Rs 605
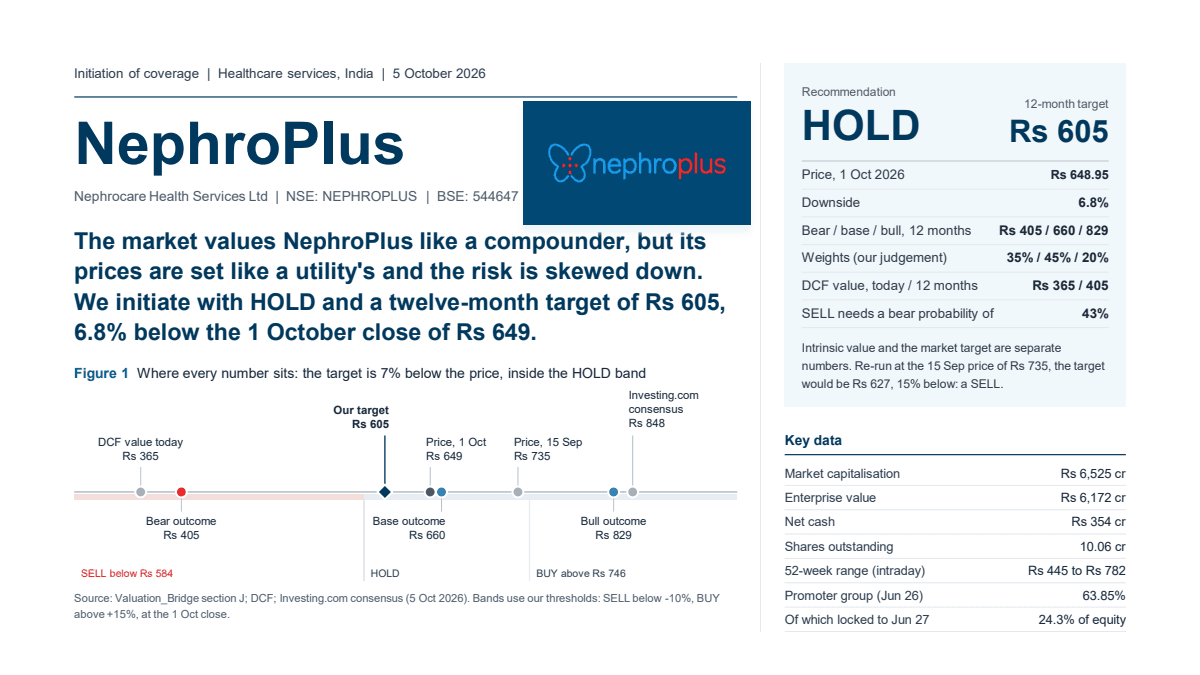
- 12-month target, 6.8% below the 1 Oct 2026 close
- Rs 365
- DCF value today, 44% below the price
- 9.3%
- after-tax return on a captive clinic, against a 10.9% cost of capital
DCF value, today
Rs 365
Bear, 35%
Rs 405
Target, 12 months
Rs 605
Price, 1 Oct 2026
Rs 649
Base, 45%
Rs 660
Bull, 20%
Rs 829
Consensus, 4 analysts
Rs 848
Where every number sits, in rupees a share. The DCF is intrinsic value today; the three outcomes are for September 2027 and, weighted, give the target, 6.8% below the price and inside the HOLD band of -10% to +15%. The base case sits above the price and the target below it because the bear case carries 35%.
Source: The metrics above and findings 4 and 5; the report's Figure 1
Overview
HOLD, with a 12-month target of Rs 605, 6.8% below the 1 Oct close of Rs 649, on India's largest dialysis chain. The market pays a growth stock's multiple, but 76.5% of patients are on public insurance and published scheme and tender rates reproduce about nine tenths of an Indian session. The network runs 550 clinics for 38,262 patients, with 45% of revenue abroad. Built from clinic-level returns, a DCF, peer multiples and a Monte Carlo; the DCF puts intrinsic value at Rs 365, three outcomes for September 2027 set the target, and the report keeps the two numbers apart. An independent student exercise in the format of the CFA Institute Research Challenge; not investment advice.
Findings
Government payers set the price. India realisation went from Rs 1,787 in FY25 to Rs 1,802 in Q1FY27, so the rise in group realisation is mix rather than pricing power
Indian growth barely clears its cost of capital. A captive clinic earns 9.3% after tax against 10.9% and a PPP clinic 2.3%. FY27 free cash flow is Rs 5 cr after acquisitions; on I-Sec's definition, which leaves them out, the report gets Rs 74 cr against I-Sec's Rs 118 cr
Cheap on EBITDA, dear on EBIT. Against six Indian hospital chains the stock trades at 26.2x EV/EBITDA against 30.1x and 44.0x EV/EBIT against 38.7x, with the heaviest depreciation in the set at 9.1% of revenue
The DCF and the target answer different questions. Only 157 of 10,000 Monte Carlo draws reach the price, yet a simple version of the same DCF puts seven listed peers at 17% to 36% of market value, so the gap is partly about the lens. It enters the target once, as the bear case
The rule that changes the call is stated. Bear Rs 405 at 35%, base Rs 660 at 45%, bull Rs 829 at 20%. SELL needs 43% on the bear, and at the 15 Sep price of Rs 735 the call would have been a SELL. Investing.com consensus is Rs 848 from 4 analysts. Q2FY27 results, due by 14 November, are the first test