06Credit
Dynamic Debt Covenant Surveillance Engine
Translating credit agreements into programmatic surveillance models for private credit.
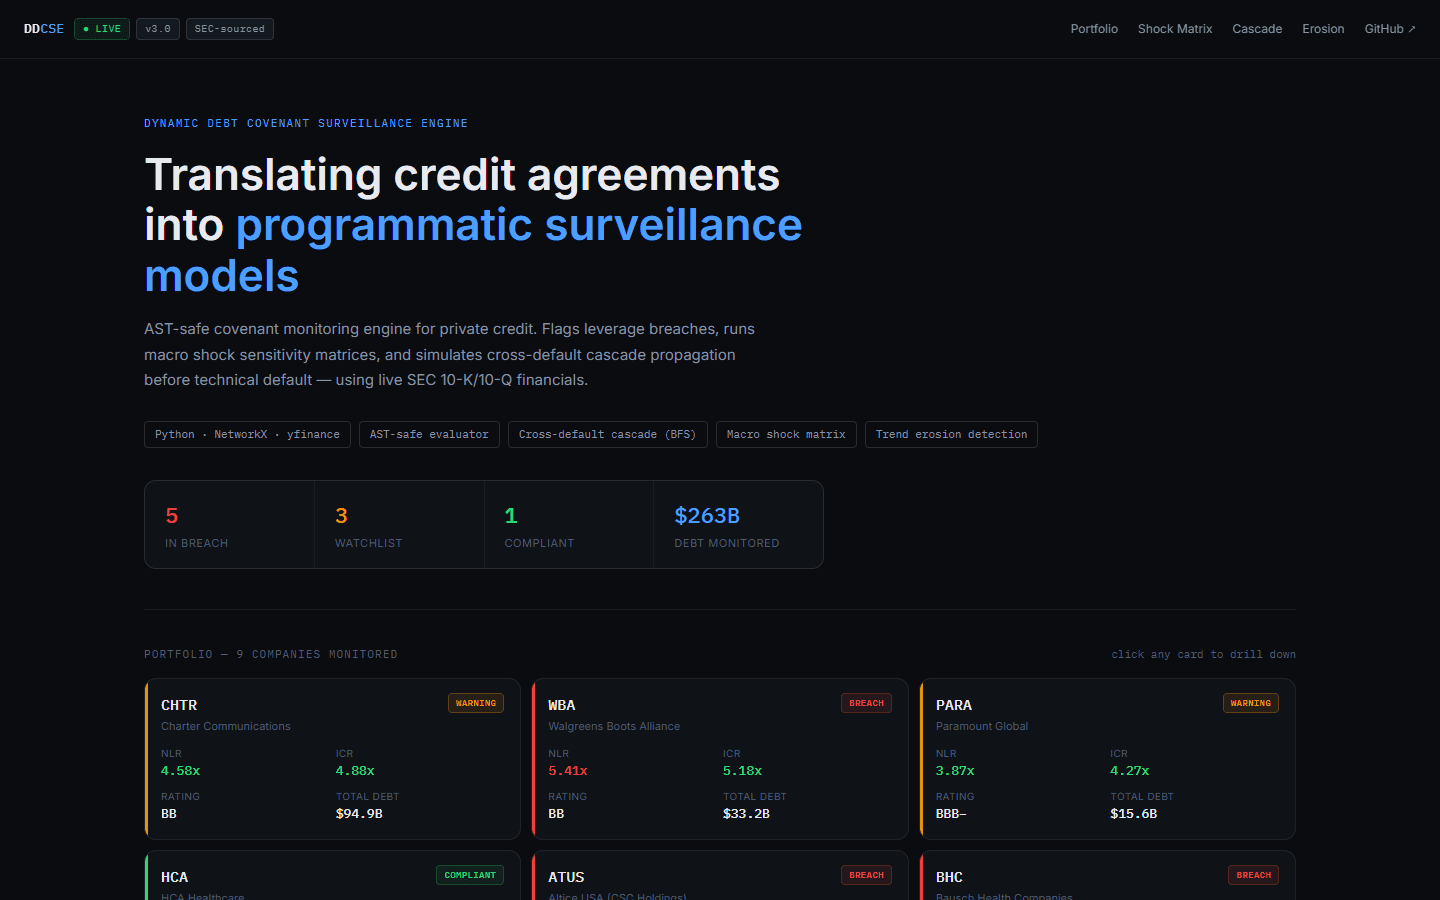
An AST-safe covenant monitoring engine that flags leverage breaches, runs macro shock sensitivity matrices, and simulates cross-default cascade propagation before technical default, using live SEC 10-K/10-Q financials across a $263B monitored debt portfolio.
- Domain
- Credit
- Artefact
- Dashboard
- Basis
- monitors $263B of issuer debt
- Stack
- Python · NetworkX · yfinance · SEC EDGAR · React
What it produced
- $263B
- debt monitored
- 9
- issuers tracked live
- 5
- covenants in breach
The problem
Private credit teams monitor covenants manually, spreadsheet by spreadsheet. Breaches surface after the fact, and cross-default clauses mean one breach can cascade through a capital structure before anyone models it.
The approach
Covenant formulas from real credit agreements are parsed into an AST-safe evaluator (no eval, no injection surface) and re-computed against live SEC 10-K/10-Q financials. A BFS pass over the intercompany guarantee graph simulates cross-default cascades, while a macro shock matrix stress-tests net leverage under rate and EBITDA scenarios.
What it found
9 issuers monitored across $263B of total debt: Charter, Walgreens, Altice, Bausch, Lumen and more
AST-safe covenant evaluator: credit-agreement math as code, without eval() risk
Cross-default cascade simulation via breadth-first search over guarantee networks
Macro shock sensitivity matrix and covenant-headroom erosion trend detection