Capital Markets Intelligence Platform
IPO event studies, sovereign risk scoring, M&A screening, and yield-curve decomposition, with zero API keys.
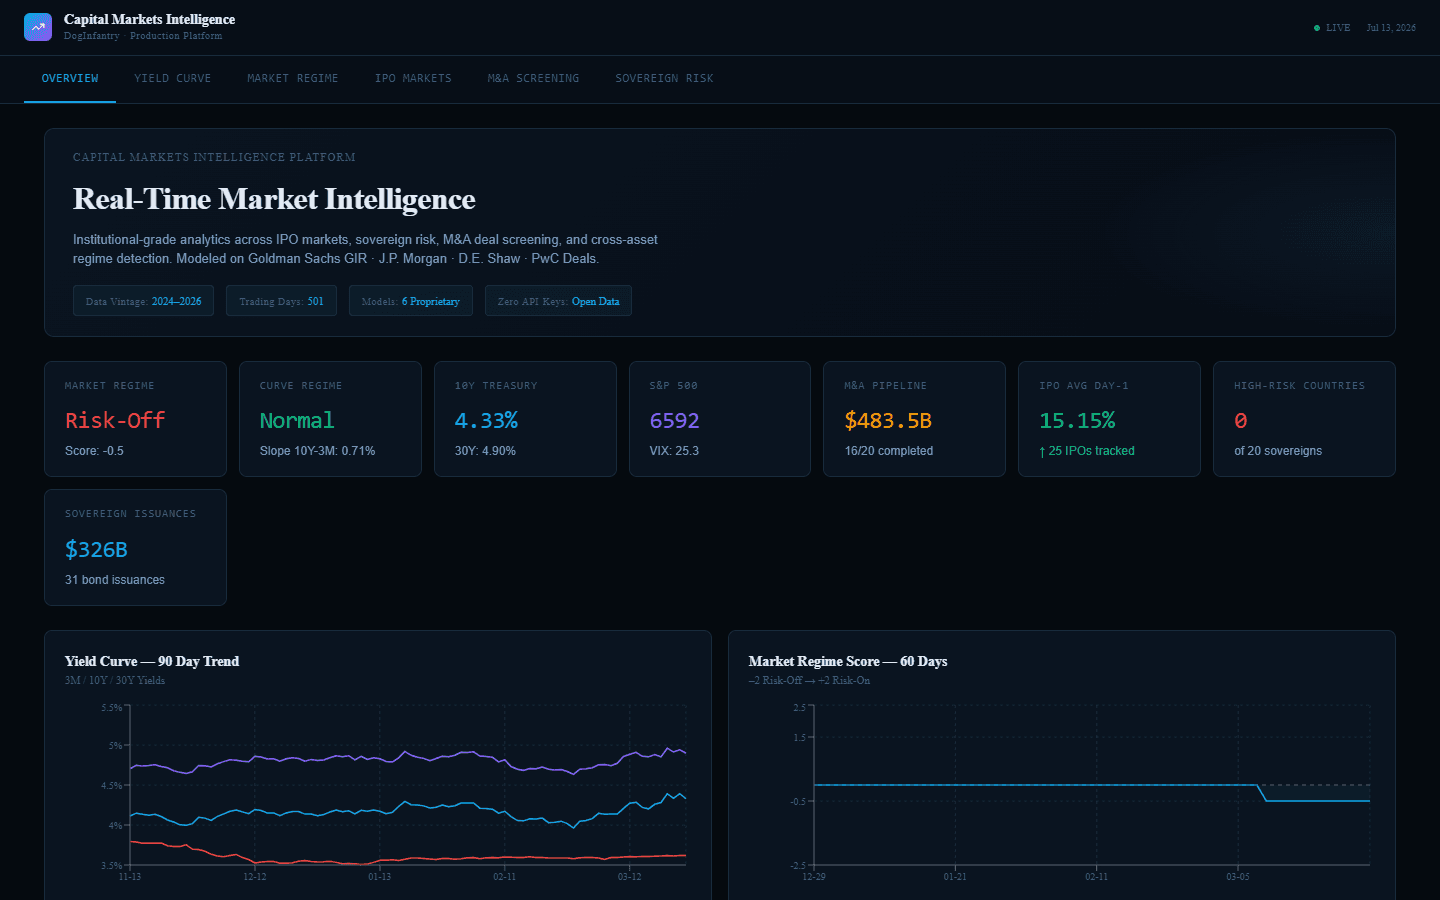
A production-grade market intelligence platform modeled on Goldman Sachs GIR, J.P. Morgan, D.E. Shaw and PwC Deals workflows: six proprietary models across 501 trading days of open data, with cross-asset regime detection on top.
- Domain
- Macro & Markets
- Artefact
- Dashboard
- Basis
- event-studies 25 IPOs on open data
- Stack
- Open market data · React · Recharts · Event-study models
What it produced
- $483.5B
- M&A pipeline screened
- 25
- IPOs event-studied
- 20
- sovereigns risk-scored
The problem
Institutional market intelligence is locked behind terminals and paid data feeds. The analytical frameworks themselves (regime scoring, curve decomposition, event studies) are reproducible with open data.
The approach
Six models built entirely on open data (no API keys): a cross-asset market regime score, yield-curve regime classification with slope decomposition, IPO day-1 event studies across 25 offerings, a 20-deal M&A pipeline screen, and macro-based sovereign risk scoring for 20 sovereigns and $326B of issuance.
What it found
Market regime score (–2 risk-off to +2 risk-on) tracked over rolling 60-day windows
Yield curve 90-day trend with 3M/10Y/30Y decomposition and regime classification
$483.5B M&A pipeline screened, 25 IPOs event-studied (avg day-1 pop 15.15%)
Sovereign risk tiers across 20 countries from growth, inflation and debt/GDP data